Through an exclusive unlisted property fund, eligible investors have the opportunity to gain exposure to The Glen Shopping Centre in Melbourne, benefiting from potential regular rental income and long-term capital appreciation. The fund proposes to acquire a 50% freehold interest in the shopping centre for approximately AUD 327.5 million, alongside Vicinity, which will retain the remaining 50% ownership interest and continue to manage the property.
Investors participate by subscribing for units in the fund, which will hold the property interest and oversee financing, asset management and income distributions. This structure allows investors to access commercial property investment without directly purchasing or managing the shopping centre.
An Established Shopping Centre with an Existing Income Base
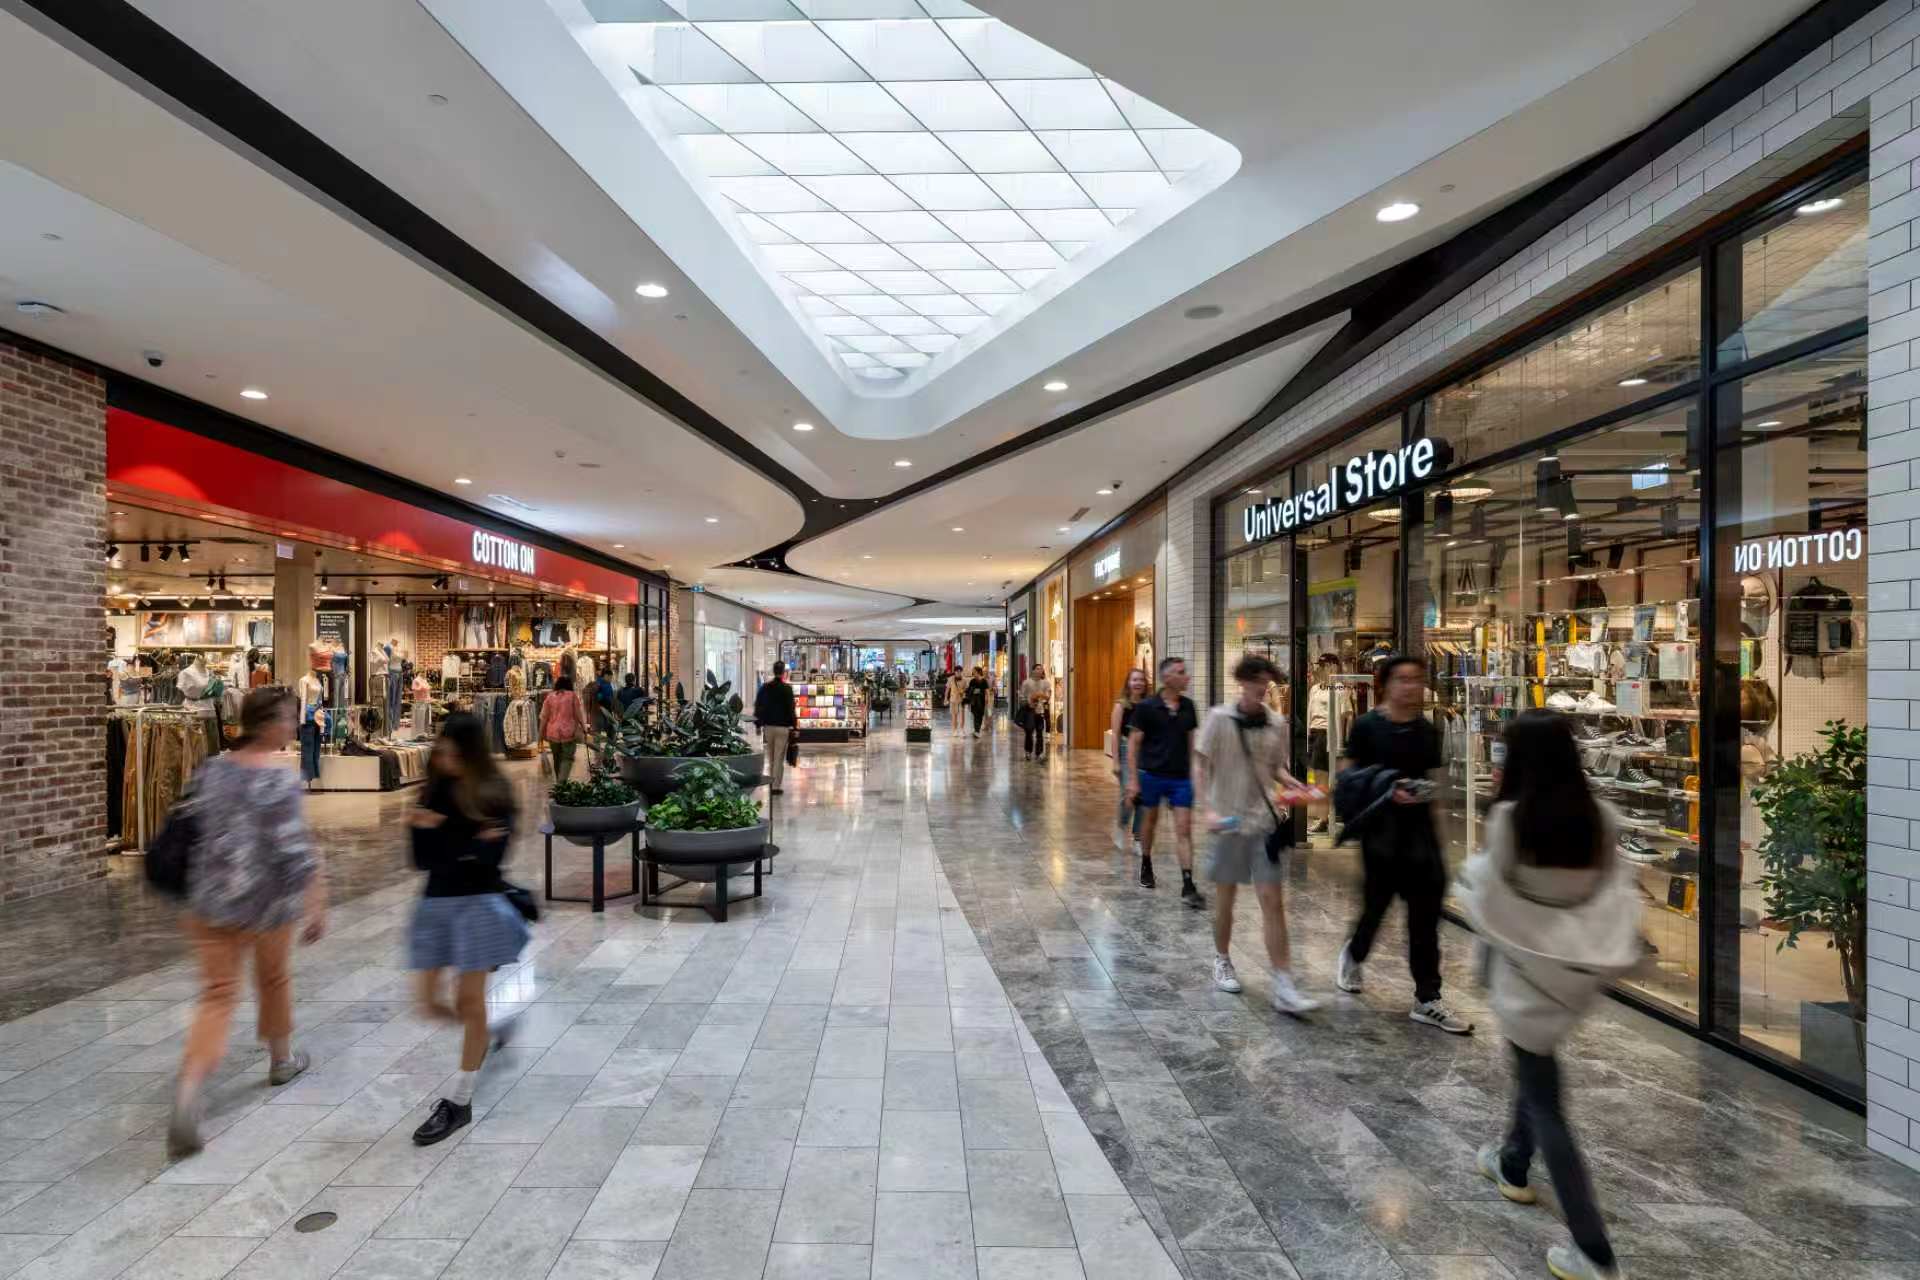
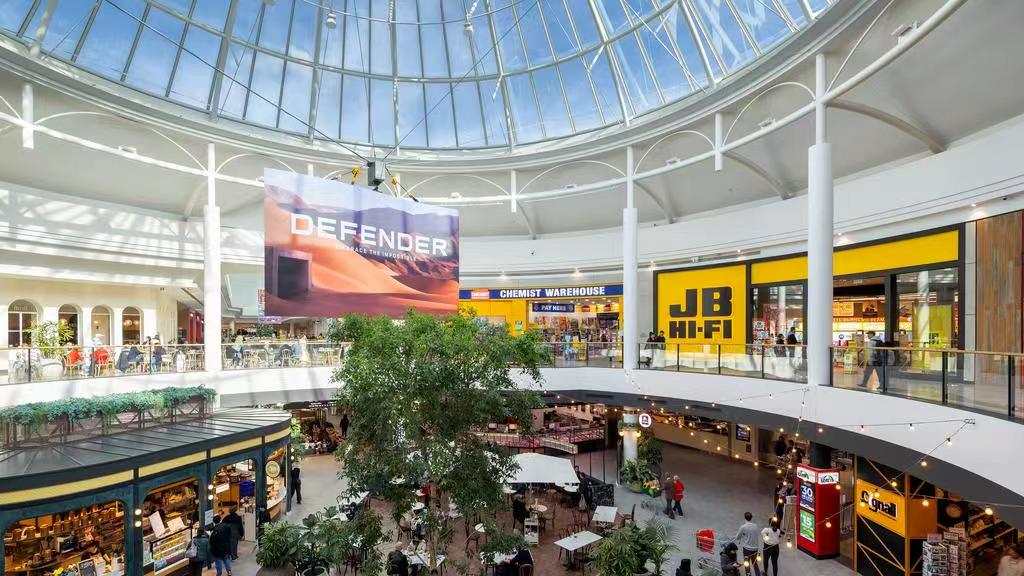
Located in Glen Waverley, south-east Melbourne, The Glen Shopping Centre comprises approximately 76,471 sqm of gross lettable area and around 3,300 car parking spaces. The centre offers a diverse mix of supermarkets, fashion retailers, dining establishments and lifestyle services.
The property has a reported occupancy rate of approximately 99% and attracts around 14.8 million customer visits annually. For the rolling 12 months to June 2026, total tenant sales reached approximately AUD 581 million. Major tenants include Coles, Woolworths, ALDI, David Jones and Target. Tenant sales provide an indication of the centre’s trading performance but are distinct from the rental income received by the fund.
The shopping centre underwent a major redevelopment costing approximately AUD 430 million in 2019–2020, enhancing its retail, dining and communal spaces. The investment opportunity is therefore supported by an established operating asset, while retaining potential for future leasing improvements and space optimisation.
Quarterly Cash Distributions and Long-Term Capital Growth
The investment’s principal target metrics are outlined below:
| Metric | Target or Projection |
| Average Annual Cash Distribution Rate | Approximately 7.5% p.a. |
| Distribution Frequency | Quarterly |
| Overall Annualised Internal Rate of Return (IRR) | 14%–15%, after fees and before tax |
| Base-Case Model IRR | Approximately 14.17% |
| Projected Total Equity Multiple | Approximately 1.86x initial investment |
| Target Investment Horizon | Approximately 5 years, subject to extension |
Cash distributions are expected to be funded primarily by the property’s operating cash flow, after servicing debt interest, paying fund expenses and allowing for capital expenditure and cash reserves. The 7.5% annual distribution rate represents an average target over the forecast period. Actual distributions may vary from year to year and should not be interpreted as fixed interest payments. IRR measures the annualised return across all investment cash flows, taking into account the timing of the initial investment, quarterly distributions and final exit proceeds.
Accordingly, the targeted IRR of 14%–15% already incorporates distributions received during the holding period. The 7.5% distribution rate should not be added separately to the IRR. For illustration, an investment of AUD 500,000 would generate an average annual cash distribution of approximately AUD 37,500, assuming the 7.5% target is achieved. If the projected total equity multiple of 1.86x is achieved, cumulative distributions and final exit proceeds would amount to approximately AUD 930,000, including the original invested capital.
These figures are illustrative calculations based on target assumptions. Actual distribution amounts and payment timing may differ.
Return Drivers: Existing Income, Operational Growth and Exit Valuation
Existing Property Income
The proposed acquisition reflects an existing net operating income yield, or passing yield, of approximately 7%. Passing yield represents the property’s current net operating income relative to its acquisition price, before accounting for fund-level financing and other expenses.
It is a property-level return metric and should not be confused with the cash distribution rate payable to investors.
Rental and Operational Growth
The management team intends to enhance net operating income (NOI) through lease adjustments, tenant repositioning and optimisation of the tenant mix.
Most specialty retail leases reportedly include annual rental increases of approximately 5%. However, these arrangements do not apply to all tenants and should not be interpreted as a guarantee that the shopping centre’s overall NOI will increase by 5% annually.
Final Exit Valuation
The base-case financial model assumes a sale after approximately five years, applying an exit capitalisation rate of 5.5%. All else being equal, higher NOI and a lower capitalisation rate would support a higher property valuation. The targeted IRR therefore depends on both operational growth and market pricing at the time of exit.
If the actual exit capitalisation rate is higher than assumed, investment returns may fall below the targeted level.
Existing Leases and Potential Space Optimisation
According to the project’s Information Memorandum (IM), Target’s lease expires in April 2032, while David Jones’ lease expires in July 2034. Both tenants have further lease extension options.
The management team will assess the long-term utilisation of these major tenant spaces, alongside opportunities to lease or repurpose approximately 4,899 sqm of vacant office space. Any potential improvements will depend on existing lease obligations, negotiations with tenants, leasing timeframes and refurbishment costs. These initiatives represent potential value-enhancement opportunities rather than confirmed additional income. The proposed acquisition price also represents a discount of approximately 16.1% to the historical peak book valuation recorded in December 2019 under the joint ownership structure.
This comparison is based on a historical peak valuation and does not represent a discount to the property’s current independent valuation.
Investment Horizon, Financing and Participation Structure
The fund intends to raise approximately AUD 193.2 million in equity capital, supplemented by bank debt, to finance the acquisition and associated transaction costs.
The initial acquisition loan-to-value ratio (LVR) is expected to be approximately 50%, with an initial debt term of around three years. The fund also intends to hedge 100% of the initial debt exposure against interest rate movements, with the model assuming that the hedging arrangements will cover at least the initial loan term. The fund has a target investment horizon of approximately five years, with potential exit opportunities expected to be assessed between years five and seven following settlement.
However, there is no fixed maturity or guaranteed exit date. Refinancing costs after the third year, future capital expenditure requirements and prevailing market conditions at the time of sale may all affect cash distributions and overall investment returns.
Tax Considerations and Fees
The project forecasts that cash distributions over the initial five-year period will be 100% tax-deferred.
Tax-deferred distributions do not necessarily constitute tax-free income. Such distributions may reduce the cost base of an investor’s fund units, potentially affecting future capital gains tax liabilities. The actual tax treatment will depend on the fund’s annual tax statements and each investor’s individual tax circumstances.
Investors should seek independent professional tax advice regarding their specific circumstances.
Enquire About the Investment Opportunity
For further information about the investment opportunity, fund management arrangements and current subscription requirements, please contact Candour Capital.
This material is provided for general information purposes only. All distribution rates, IRRs, equity multiples and exit timelines are projections or targets and are not guaranteed. Changes in property operating performance, leverage and market valuations may result in a partial or total loss of invested capital.
Disclaimer
This material is intended solely for wholesale clients as defined under section 761G of the Corporations Act 2001 (Cth) and is not intended for retail investors. The information contained in this material is general in nature and does not take into account the investment objectives, financial circumstances or particular needs of any individual. Certain company financial information, valuations and IPO-related information referred to in this material have been sourced from publicly available third-party reports and may be subject to change. Target returns, potential IPO valuations and anticipated investment horizons are not guaranteed. Pre-IPO investments and investments in unlisted equity involve significant risks and relatively low liquidity. An IPO may be delayed, postponed indefinitely or may not proceed at all, and investors may lose some or all of their invested capital. Before making any investment decision, investors should read the formal investment documents and seek independent legal, taxation, financial and accounting advice appropriate to their circumstances.